The Used Car Buyer’s Complete Fraud Prevention Playbook
Every fact, figure and legal citation in this article was checked against its original source before publication by Artūras Andriušaitis, founder and editor. Editorial Standards
A used car is one of the largest purchases most Americans make outside of a home, and it comes with far less protection than a new one. State lemon laws are written for new cars, and only a few states extend them to used ones. Insurance does not retroactively cover undisclosed damage. By the time the buyer drives away, the seller’s job is done, and a problem found afterward is far harder to fix than one caught before the sale.
This playbook walks through the full process of buying a used car without getting scammed. It is a guide to how to avoid used car scams at every stage: the research before the visit, the in-person checks at the meeting, the independent inspection, the negotiation, the paperwork review, and the payment and post-sale steps. The structure follows the buyer’s actual timeline, because fraud at each stage looks different and requires different defenses.
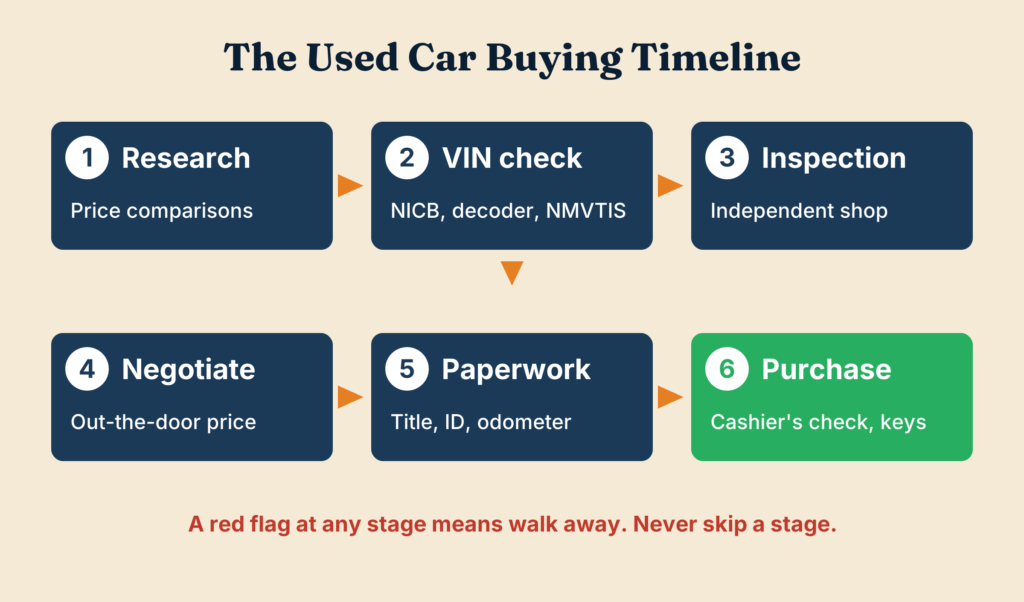
Research the Car Before the Visit
The work that protects buyers from fraud starts before any meeting takes place. Most of it is free. Skipping it is a common route to buyer’s remorse, because once a buyer is standing in front of a car they have driven across town to see, the pressure to commit grows by the minute.
Start with market price research. Pull the same year, make, model, and trim from Kelley Blue Book and Edmunds, and check three to five comparable listings on AutoTrader, Cars.com, and Facebook Marketplace. A car priced significantly below market is one of the most reliable warning signs in used-car sales. Sellers do not give away thousands of dollars by accident. The price is either a flag for a problem the seller is hiding or a signal that the listing itself is a scam designed to lure deposits from buyers who never see the car.
Next is the VIN check. Run the 17-character vehicle identification number through NICB VINCheck, which is free, takes thirty seconds and allows five searches a day. NICB checks the VIN against the theft and salvage records reported by participating insurers, and a flag here ends the conversation. Then decode the VIN through NHTSA’s free decoder, which returns make, model, year, body class, engine and trim, and compare it with the listing: a mismatch is either a typo or a misrepresentation to raise at once. Buyers who decode the VIN before you visit walk into the meeting with a baseline of facts the seller cannot rewrite on the spot.
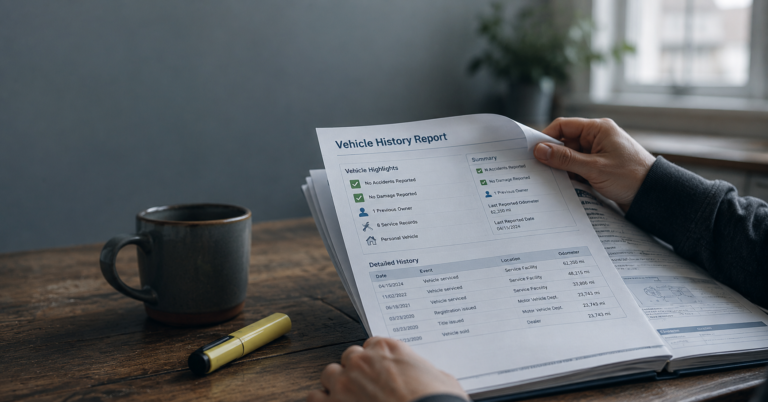
The third piece of pre-visit work is the paid NMVTIS report, about $10 from a provider on the Justice Department’s list. It covers the title brand history, the most recent odometer reading in the title record and the earlier states of title, which is where a brand dropped between two states shows up. We cover how to run a free VIN check in detail in a separate piece, including where the free tools stop and the paid report begins.
If the seller refuses to provide the VIN before the meeting, treat that as a final answer rather than a negotiation point. Honest sellers want educated buyers because educated buyers close transactions. The only sellers who hide the VIN are the ones who know what a VIN check would reveal. Mileage on the report that does not match the odometer is one of the diagnostic patterns to look for, and is one of the reasons why odometer fraud still works decades after federal disclosure rules took effect.
What to Inspect Yourself on the First Look
Arrive at the meeting prepared. Bring the vehicle history report, a flashlight, a portable OBD-II reader if you have one, and a phone for photographs. Schedule the meeting in daylight. Inspecting a car at night under fluorescent lighting hides corrosion, mismatched paint, and water lines that daylight reveals immediately.
Meet at the seller’s home for a private sale, not at a parking lot or a gas station. A seller who refuses to meet at home may be concealing that the car is not theirs to sell, which is the textbook profile of how to spot a curbstoner before the conversation has even started. If the seller is simply wary of strangers at the door, a bank lobby or a police department’s safe exchange zone is the fair alternative.
The first physical check is VIN verification. The dashboard VIN plate is visible through the windshield on the driver’s side. The door jamb sticker shows the same VIN plus the federal certification label. The engine often carries another marking that some inspectors will check, in some cases only the final characters of the VIN (at least the last eight). The dashboard, the door jamb, any engine marking, and the title document itself should all agree. Mismatches across these locations indicate a clone, a stolen vehicle, or paperwork that has been altered. Photograph the dashboard plate and the door jamb sticker before any other inspection.
Walk the exterior. Look for paint tone differences between body panels, especially on the doors, fenders, and quarter panels. Subtle color mismatches indicate a repaint, which usually indicates collision repair. Run a fingertip along the gaps between panels. Uneven gaps are a tell for a frame-damage rebuild. Check the underside of the doors and the lower edges of the fenders for rust on bolts that should still be factory-fresh. Open the hood and trunk and look for water lines, mud residue inside the spare tire well, and corrosion on electrical connectors. Those are the diagnostic signatures of a flood vehicle, and a detail wash often leaves some of them behind.
Take the car on a real test drive, not a loop around the block. Drive at highway speed to test steering, brakes, and any vibration. Test every electrical system in sequence, including windows, locks, AC, heat, infotainment, and all warning lights. Listen for transmission slips on acceleration. Test the brakes hard once on an empty road. Even a long drive cannot rule out flood damage. The FTC warns that water damage can slowly destroy mechanical and electrical systems, which is why the test drive never replaces a mechanic’s inspection.
The conversation during the visit deserves as much attention as the physical inspection. Our 10 questions to ask before buying covers the specific prompts that distinguish honest sellers from evasive ones. Ask all of them, listen to how the answers come, and trust the pattern of the answers as much as their content. Private sellers in particular tend to give themselves away in this conversation, and the red flags with private sellers are a subject of their own: the seller who will not meet at home, will not share the VIN, or wants a deposit before a viewing.
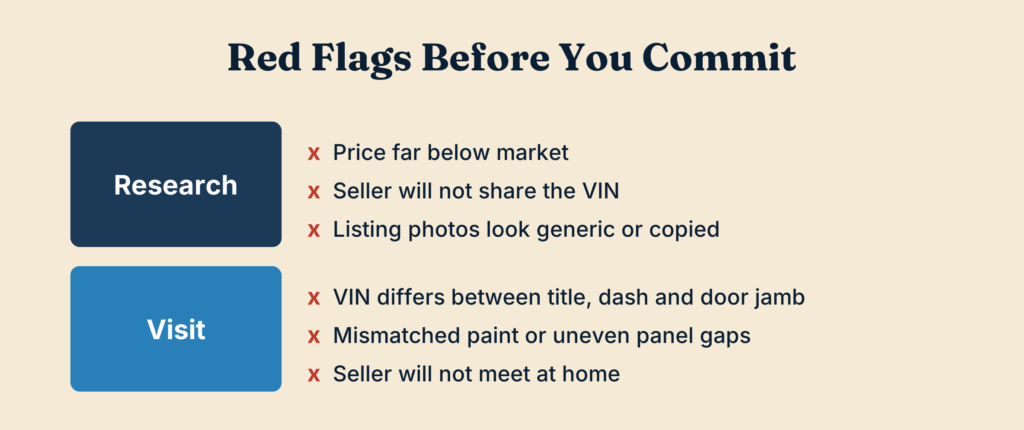
The Pre-Purchase Inspection Is the Most Important Step
The single most effective fraud defense available to a used-car buyer is the pre-purchase inspection. It costs $100 to $200, takes about an hour, and catches problems that no number of test drives or VIN checks can find. The Federal Trade Commission recommends a pre-purchase inspection for any used-car purchase, and the National Insurance Crime Bureau gives the same advice in its buyer guidance.
The inspection has three rules. First, it must be by an independent mechanic, not the seller’s mechanic and not the dealership service department. The whole point is an outside opinion that has no financial relationship to the sale. Second, the buyer pays for it. The cost is small enough that paying it directly is straightforward, and avoids any ambiguity about who the mechanic is working for.
Third, the inspection happens where the buyer’s mechanic can do it properly. That is the mechanic’s shop or, if a dealer cannot release the car, the lot itself through a mobile inspection service, which the FTC suggests for that case. A “we already inspected it” or “you can have it checked after you buy it” answer is a refusal, regardless of the framing.
Find an independent shop ahead of time. Look for shops certified by the relevant manufacturer (Honda buyers want a Honda specialist) or general independent garages with strong reviews on Google and Yelp. Call ahead to confirm they perform pre-purchase inspections, what the inspection includes, and what they charge. Most shops will provide a written report covering the engine, transmission, brakes, suspension, frame, tires, fluids, and electronics, plus any signs of accident repair, flood damage, or odometer tampering. Consumer Reports’ used-car inspection checklist outlines what a thorough mechanic should be looking for; the full scope is a detailed pre-purchase inspection handbook in itself, and this playbook covers only the rules for ordering one.
A confident seller, whether private or dealer, will allow this. A seller who refuses, delays, or attaches conditions (“only by our own mechanic,” “only after a non-refundable deposit”) is filtering themselves out of the market. Walking away from a refused inspection costs nothing. Buying a car the seller would not let an independent mechanic touch costs whatever the eventual repair bill turns out to be, which is rarely small.
The inspection’s value is not just diagnostic. It also resets the negotiation. A pre-purchase inspection that surfaces $1,200 in immediate repairs gives the buyer a documented basis to negotiate the price down by that amount, or to walk. The shop’s report becomes evidence in any subsequent dispute. Buyers who skip the inspection give up both the diagnostic information and the negotiating advantage at once, often without realizing they did either.
Negotiating Without Getting Played
Negotiation in used-car sales is structured to favor whoever has more information. The buyer’s advantage is that they walked in prepared. The seller’s advantage is that they have done this many more times. Closing the gap requires knowing where dealers and private sellers make their money, and refusing to engage on terms that hide it.
The most important number in any negotiation is the out-the-door price. This is the total amount the buyer will hand over, including the vehicle price, all dealer fees, all taxes, all registration costs, and any add-on products. Sellers who quote monthly payments instead of out-the-door prices are running the math on the buyer’s side of the table. Stretch a $25,000 car over 84 months at 9 percent interest and the monthly payment looks affordable; the total cost is approaching $34,000. Always negotiate the out-the-door price first, then discuss financing separately if relevant.
Dealer fees deserve specific scrutiny. Documentation fees vary by state but commonly range from under $100 to about $1,000, with some states capping them and others not. Some dealers add reconditioning fees, advertising fees, vehicle preparation fees, and “market adjustment” surcharges that have no basis in cost. Push back on each line item. Ask what specifically the fee covers. Walk away if the math does not justify the line. State law may also entitle the buyer to a written breakdown of every fee, depending on jurisdiction.
Add-on products are where dealers make significant margin. Extended service contracts, gap insurance, paint protection, fabric protection, theft etching, and nitrogen-filled tires are all sold at high markup. Some have value in specific situations; most do not. The salesperson is incentivized to bundle them in such a way that declining one feels like declining the whole deal. It does not. Each add-on is its own decision, and the buyer can decline any or all of them without affecting the underlying purchase.
Trade-in valuation is the other classic margin maneuver. Get a written trade-in offer from CarMax, Carvana, or another aggregator before visiting the dealer, then use that figure as the floor in any trade-in conversation. Without the outside number, the dealer’s offer becomes the only data point, and Kelley Blue Book notes that dealers often open with a little less than the car’s wholesale value.
The strongest negotiation position is willingness to walk away. The buyer who has researched the market, run the VIN, completed the inspection, and verified the paperwork has nothing to lose by leaving and trying again with a different car. The seller who has invested time in the transaction has more to lose. Most aggressive negotiation pressure depends on the buyer not knowing this. Knowing it changes the dynamic entirely.
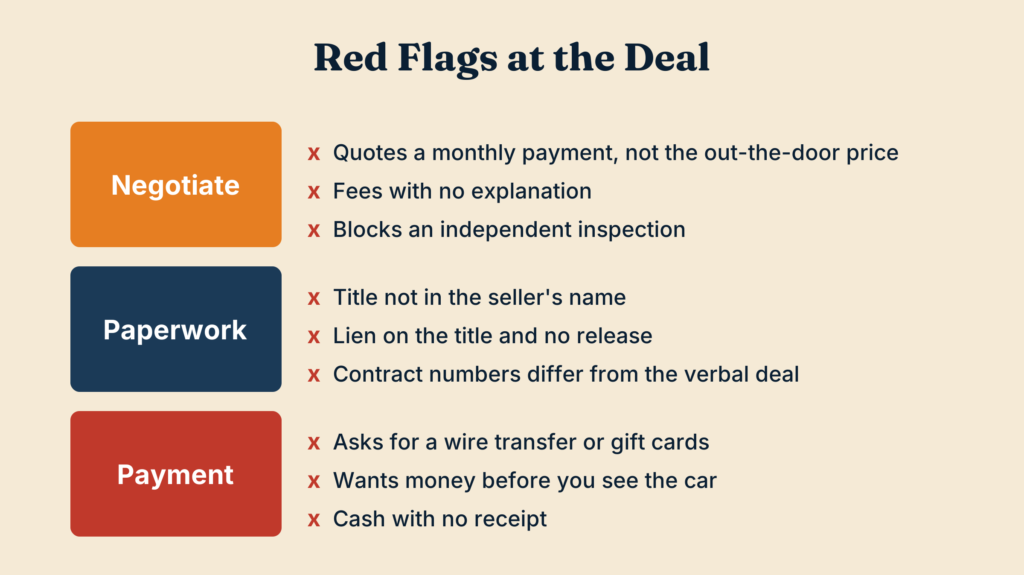
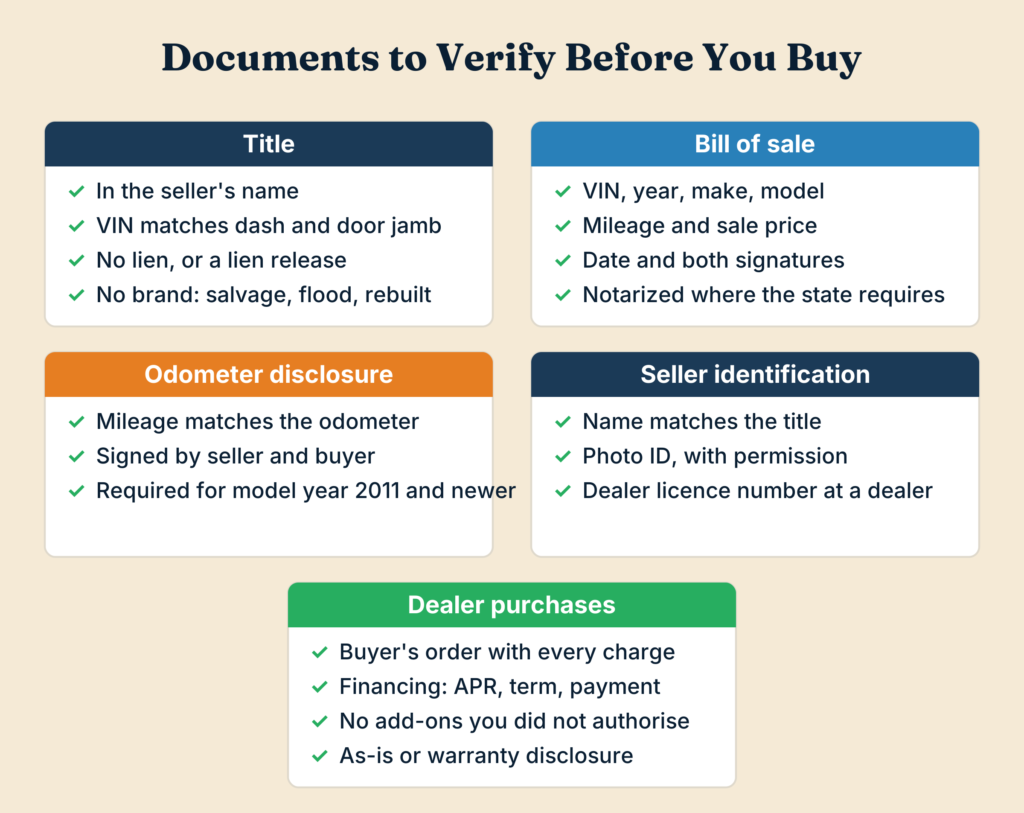
Paperwork to Verify Before Money Changes Hands
Once the price is settled, the paperwork phase begins. This is the stage where rushed buyers make mistakes that cost them years to unwind. Read every document before signing. Verify every name, every VIN, every dollar amount.
The title is the central document. Verify that the title is in the seller’s name (matching their photo ID), that the VIN on the title matches the VIN on the dashboard plate and door jamb, and that the title is free of any lien indication.
Some states hold titles electronically. An electronic title is a record in the state’s system, not a document, and Florida, for example, states that titles cannot be printed at home. Depending on the state, the seller orders the paper title before the sale, or the transfer is completed at the motor vehicle office or in the state’s own online system. Either way, the proof of ownership is the state’s record, not a screenshot or a printout.
A title with a lien marked on it means a lender still has a claim on the car. Buying it without a lien release means the lender can repossess the vehicle from the new owner. We cover how title washing hides a car’s history in detail in a separate piece, with specific guidance on cross-state title histories that should trigger additional scrutiny.
The bill of sale records the transaction. It should include the VIN, year, make, model, mileage, sale price, date, and signatures of both parties. Some states require notarization. The bill of sale is also the buyer’s evidence of the agreed-upon condition and disclosures, which matters if the seller misrepresented the vehicle. Keep the original.
The federal odometer disclosure is required on the sale of any car of model year 2011 or newer, and is normally made on the title itself. A dealer may use a state reassignment form instead, and with an electronic title the reading goes into the state’s own system or form. Cars of model year 2010 and older are exempt, and newer ones stay covered for 20 years, so a 2011 model drops out in 2031.
The seller writes in the mileage and signs that it is the actual mileage to the best of their knowledge, or checks one of two boxes: that the odometer has passed its mechanical limit, or that the reading is not the actual mileage. The buyer signs as well. A seller who has to make the odometer disclosure and cannot or will not do it is admitting something. The federal statute creates both civil and criminal penalties for false disclosures, which is one reason most sellers handle this paperwork carefully.
For dealer purchases, the documents multiply. There will be a buyer’s order itemizing every charge, a financing contract if relevant, an as-is or warranty disclosure, and various add-on agreements. Read each one. The financing contract is the longest and most consequential document; verify the APR, the loan term, and the monthly payment match what was negotiated, and that no add-ons were included that the buyer did not authorize. Dealers occasionally insert charges into the contract that were not in the verbal negotiation. Catching this requires reading the contract before signing it.
The seller’s identification matters as much as the title itself. Match the name on the title to the name on the seller’s driver’s license. Photograph the seller’s ID with their permission. For private sellers, this protects against meeting an identity thief who is selling someone else’s car. For dealer purchases, verify the salesperson’s name and the dealership’s license number for any future correspondence.
Payment, Possession, and Aftermath
Payment method choice protects the buyer in the final step. The safer methods are a cashier’s check from the buyer’s own bank or, for higher-value transactions, an escrow service the buyer chooses. A careful seller will want to verify a cashier’s or certified check with the issuing bank and may ask to meet at that bank, which is a reasonable request. Forged cashier’s checks have been a known scam pattern against sellers for two decades, and they keep working because banks are slow to flag them on the same day they are presented.
The riskier payment methods are wire transfers requested by the seller, cash without a receipt, and any payment involving gift cards or cryptocurrency. The Federal Trade Commission flags wire transfers and gift cards as the signature payment requests of vehicle scams. No legitimate used-car seller asks for payment in Apple gift cards or Google Play cards. Any request along those lines means the listing is a scam regardless of how plausible everything else looks. Walk away.
Possession means physical handover plus paperwork transfer in the same meeting. Confirm that the seller hands over the original title (not a photocopy), all keys including any spare and valet keys, both key fobs if applicable, the owner’s manual, the service records, and any tools or equipment listed in the manual. Where the title is electronic, the completed state transfer takes the place of the paper. Some private sellers ship with the spare tire missing or a fob deactivated; both are easier to address before the handover than after. The same applies to anything missing from the listing photos. If the listing showed roof rails or a cargo cover and the car arrives without them, raise it before signing.
Most states set a deadline, typically 10 to 30 days, for the buyer to register the vehicle and transfer the title. Insurance must be in place before the buyer drives the vehicle off the seller’s property. Most insurance companies issue a binding coverage confirmation within minutes by phone or app.
A buyer with no policy who skips this step is uninsured for the drive home, which is illegal in most states and exposes the buyer to liability if a collision happens between purchase and the home driveway. A buyer who already has an auto policy may be covered automatically for a short time, about 20 days in Texas according to the state’s insurance regulator, and should still tell the insurer at once.
Post-sale fraud detection still matters. If the vehicle history report or NMVTIS check returns information after purchase that contradicts what the seller represented, including a salvage record that surfaces or a flood brand from a prior state, the buyer has options. State consumer protection laws and federal odometer fraud statutes both create civil and criminal remedies. Document everything: the listing, the conversation with the seller, the bill of sale, the title, the inspection report, and any photos taken at the meeting. Contact the state attorney general’s consumer protection division or the FTC if the seller appears to have committed deliberate fraud.
For dealer purchases that go wrong, the used car lemon laws of a few states and motor vehicle dealer regulations may provide additional protections. The Better Business Bureau, the state DMV, and the state attorney general all accept complaints against dealers, and a consistent pattern of complaints can trigger investigation. The buyer’s evidence, including the contracts, the inspection report, and any documented misrepresentations, determines what those investigations can do.
Frequently Asked Questions
What is the first thing I should do before buying a used car?
Run the free NICB VINCheck at nicb.org/vincheck, which checks the VIN against participating insurers’ theft and salvage records in about thirty seconds. Then decode the VIN through NHTSA’s free decoder to confirm the car’s identity matches the listing, and buy an NMVTIS report, about $10 from a provider on the Justice Department’s list, for the title brand history.
Should I get a pre-purchase inspection even from a dealer?
Yes, always, from an independent mechanic rather than the dealer’s own service department. The dealer’s mechanic has a financial relationship with the seller and is not the right person to deliver an honest assessment. An independent inspection costs $100 to $200, takes about an hour, and is the single most effective fraud defense available to buyers. Refusing to allow the inspection is a refusal regardless of how it is framed.
What documents should I verify before buying?
The title in the seller’s name with no lien indications, with a VIN that matches the dashboard plate and door jamb sticker. The seller’s photo ID matching the name on the title. The bill of sale with VIN, year, make, model, mileage, sale price, and both signatures. The federal odometer disclosure, signed by the seller and the buyer, for a car of model year 2011 or newer. For dealer purchases, the buyer’s order itemizing every charge and the financing contract verifying the agreed APR, term, and monthly payment.
Is it safer to buy from a dealer or a private seller?
The risks differ rather than one being uniformly safer. Dealers offer more legal protections, including the federal Buyers Guide rule, dealer licensing oversight, and structured complaint channels. Dealers also push hidden fees, add-on products, and financing markups that private sellers do not. Private sellers offer less recourse if something goes wrong but also fewer fees and add-on pressure. The right defense in both cases is the same: VIN check, independent inspection, paperwork review, and willingness to walk away.
What payment methods are safest?
A cashier’s check from the buyer’s own bank or, for higher-value transactions, a reputable escrow service the buyer chooses. Risky methods include wire transfers requested by the seller, cash without a receipt, gift cards, and cryptocurrency. Any seller who asks for gift cards or untraceable payment is running a scam regardless of how plausible the listing looks otherwise.